How to Calculate Adjusted Gross Income (AGI) as a 1099 Gig Worker
By Brenden Warn, Founder & Gig Economy Analyst · Updated May 2026
AGI for a 1099 gig worker is total income (Schedule C net profit plus any W-2 wages or other income) minus above-the-line adjustments — half of self-employment tax, SEP-IRA contributions, self-employed health premiums, HSA contributions, and student loan interest. It lands on Form 1040, line 11 — and that single number controls your federal tax bracket, ACA premium tax credit, FAFSA aid, and income-driven student loan payment. After running my own numbers on 42,000+ Lime tasks, AGI is the lever I obsess over most, because every dependent calculation moves with it.
What Is Adjusted Gross Income?
Adjusted Gross Income is total income from all sources minus a specific list of "above-the-line" deductions defined in IRS Schedule 1, Part II. For a W-2 employee, AGI usually equals wages plus a little interest, minus maybe a student loan interest deduction. For a 1099 gig worker, the calculation has more moving parts — but it also gives you far more levers to pull.
The gig-worker version starts with Schedule C net profit, which is your gross platform earnings minus every legitimate business expense — mileage, phone, supplies, platform fees. That net profit becomes part of total income on Form 1040. Then Schedule 1 adjustments (half of SE tax, retirement contributions, health insurance premiums, HSA, student loan interest) come off above the line to produce AGI.
Why "above the line"?
"The line" refers to the AGI line itself (Form 1040, line 11). Deductions taken above that line — on Schedule 1 — reduce AGI. Deductions taken below the line — the standard deduction, itemized deductions, the QBI deduction — reduce taxable income but NOT AGI. Above-the-line deductions are more valuable because AGI drives so many downstream eligibility tests.
The 5-Step AGI Calculation
Follow these in IRS form order — Schedule C first, then Schedule 1, then Form 1040. Every tax software (TurboTax, FreeTaxUSA, H&R Block) walks the same path under the hood.
Compute gross gig earnings (1099-NEC + 1099-K + cash)
Add every payout from every platform — DoorDash, Uber, Walmart Spark, Instacart, Lyft, Amazon Flex, Lime, Grubhub. Include cash tips and any earnings under the $600 1099 threshold. This is your gross revenue, not your taxable income.
Feeds Schedule C, line 1
Subtract Schedule C business deductions
Deduct mileage at the 2026 IRS rate (72.5¢/mile for January–June, 76¢/mile from July 1), phone (business-use %), supplies, hot bags, tolls, parking, platform fees, and any other ordinary-and-necessary business expense. The remainder is your net profit (Schedule C, line 31).
Schedule C, lines 8–30 → line 31 (net profit)
Add net profit to Form 1040 total income
Net Schedule C profit flows to Schedule 1, line 3, then to Form 1040, line 8. Add wages, interest, dividends, capital gains, or any other income to reach total income on Form 1040, line 9.
Schedule 1, line 3 → Form 1040, line 8 → line 9
Subtract above-the-line (adjustments to income)
These are the deductions that reduce AGI — and they're where most gig workers leave money on the table. Subtract: half of self-employment tax (Schedule SE × 0.5), self-employed health insurance premiums, SEP-IRA / Solo 401(k) contributions, HSA contributions, and student loan interest (up to $2,500). Itemized deductions and the standard deduction do NOT reduce AGI.
Schedule 1, lines 11–26 → Form 1040, line 10
Total income − adjustments = AGI= AGI
Form 1040, line 11. This single number controls your federal tax bracket, ACA premium tax credit eligibility, income-driven student loan payments, FAFSA EFC, Roth IRA contribution limits, and many other downstream calculations. Get it right or every dependent number is wrong.
Form 1040, line 11
Worked Example: A Single-Filer Dasher in 2026
Let's run the numbers for a gig driver with $52,000 in DoorDash earnings, 22,000 business miles, and an $8,400 part-time W-2 job. The $52,000 is an example, not a typical pay figure. For what delivery drivers actually earn, see our 2026 food-delivery pay analysis.
Schedule C — Net Profit Calculation
Form 1040 — Total Income
Schedule 1 — Above-the-Line Adjustments
Form 1040, line 11 — Adjusted Gross Income
Note: this driver started with $60,400 in gross income ($52,000 gig + $8,400 W-2) but lands at an AGI of $32,162. The combined Schedule C deductions plus above-the-line adjustments reduced AGI by about $28,238. The taxable income calculation comes next: AGI minus the $16,100 standard deduction (single, 2026) minus QBI deduction = taxable income on line 15. For a live model with your own numbers, use our 1099 tax calculator.
AGI vs. Taxable Income vs. MAGI
Three numbers that get conflated in conversation but mean different things on different tax forms. Getting them straight saves hours of confusion when a lender, the FAFSA, or an ACA exchange asks for a specific one.
AGI (Adjusted Gross Income)
Form/line: Form 1040, line 11
Formula: Total income − above-the-line adjustments
Used for: Federal tax bracket lookup, ACA premium tax credit, FAFSA EFC, IDR student loan payments, Roth IRA phase-out, state tax starting point in most states
Taxable Income
Form/line: Form 1040, line 15
Formula: AGI − standard deduction OR itemized deductions − QBI deduction
Used for: The actual number multiplied against the tax brackets to compute your federal income tax owed (before SE tax and credits)
MAGI (Modified Adjusted Gross Income)
Form/line: Not a single line — recomputed for each program
Formula: AGI + add-backs that vary by program (foreign earned income, student loan interest, IRA contributions, etc.)
Used for: Roth IRA contribution eligibility, ACA premium tax credit, Medicare IRMAA surcharges, Net Investment Income Tax — each program defines MAGI slightly differently
Why AGI Matters: 5 Downstream Calculations That Move With It
AGI isn't just a tax-form line. It's the input to many federal and state eligibility tests. Here are five that matter most for gig workers.
ACA Premium Tax Credit
→ Trigger: AGI between 100% and 400% of the federal poverty line (about $15,650–$62,600 for a single filer, based on the 2025 poverty guidelines used for 2026 coverage)
Your credit shrinks as AGI rises, and it drops to $0 above 400% of the poverty line. Forgetting a SEP-IRA contribution can push your AGI up and your subsidy down.
Income-Driven Student Loan Repayment
→ Trigger: Payment is a percentage of discretionary income, which is calculated from your AGI
A lower AGI generally means a lower required payment on an income-driven plan. The plan rules have been changing, so check the current terms on studentaid.gov before you plan around them.
Roth IRA contribution limit
→ Trigger: 2026 phase-out: single filers $153,000–$168,000 MAGI; married filing jointly $242,000–$252,000
Above the phase-out: $0 Roth contribution allowed. AGI directly determines whether you can fund a Roth at all that year. The backdoor Roth is the workaround.
FAFSA Expected Family Contribution (EFC) / Student Aid Index (SAI)
→ Trigger: AGI from 2 years prior is the primary input
Because the FAFSA looks back two years, above-the-line deductions you take now can affect aid later. Plan SEP-IRA / HSA contributions with that lag in mind.
State income tax
→ Trigger: Most states use federal AGI as the starting point
CA, NY, MA, NJ start from federal AGI then add their own modifications. A lower federal AGI generally = lower state taxable income. The 9 no-income-tax states (FL, TX, NV, WA, etc.) are the exception.
5 AGI Mistakes Gig Workers Make (and How to Fix Them)
These are common mistakes on self-prepared returns from gig drivers, and each one leaves AGI higher than it should be.
1. Treating gross gig earnings as income
Fix: The 1099-NEC or 1099-K number is gross revenue, not income. Net profit (Schedule C, line 31) is what flows up to total income. Forgetting business deductions inflates your AGI.
2. Forgetting to deduct half of SE tax above the line
Fix: Self-employment tax (15.3% of net earnings × 92.35%) is brutal — but half of it is an above-the-line deduction on Schedule 1, line 15. A driver netting $40,000 owes ~$5,651 in SE tax and gets a ~$2,826 AGI reduction. Skipping this line is an easy mistake on a self-prepared return.
3. Confusing AGI with taxable income
Fix: AGI is line 11. Taxable income is line 15 (AGI minus standard or itemized deductions minus QBI). When a lender, FAFSA, or ACA exchange asks for AGI, they want line 11 — not line 15.
4. Missing the self-employed health insurance deduction
Fix: If you bought health insurance through the Marketplace and aren't eligible for a spouse's employer plan, premiums are an above-the-line deduction on Schedule 1, line 17 — capped at your Schedule C net profit. Skipping it leaves AGI higher than it needs to be.
5. Not contributing to a SEP-IRA or Solo 401(k) before filing
Fix: SEP-IRA contributions (up to 20% of net SE earnings after the 1/2 SE deduction, max $72,000 in 2026) are above-the-line and can be made up to your tax filing deadline (including extensions). A contribution made before the filing deadline can lower AGI for the prior year.
For the deduction side of the equation in more detail, see our pillars on tax write-offs for gig workers and mileage and tax deductions. If you need an IRS-verified income proof for a lender or aid program once AGI is final, our tax return transcript guide walks the request process.
Sources: IRS 2026 inflation adjustments (standard deduction), IRS 2026 retirement limits (Roth IRA phase-outs), IRS defined contribution limit ($72,000), IRS Rev. Proc. 2025-19 (HSA limits), IRS Topic 456 (student loan interest), IRS self-employment tax, IRS premium tax credit Q&A, and HHS poverty guidelines.
Frequently Asked Questions
How do I calculate adjusted gross income (AGI) as a gig worker?
Where do I find AGI on my tax return?
What is the difference between AGI and taxable income?
Does the standard deduction reduce my AGI?
How can a gig worker reduce their AGI?
Do mileage deductions reduce AGI for 1099 workers?
Why does AGI matter for student loans and FAFSA?
Lower Your AGI, Year After Year
ShiftTracker logs odometer readings at shift start and end (the IRS Publication 463–compliant format) and exports a clean Schedule C summary every January. The bigger your mileage deduction, the smaller your Schedule C net profit, the lower your AGI, and the more downstream programs swing in your favor.
Related from the Blog
1099 Taxes for Gig Workers 2025: Deductions, Mileage & Quarterly Guide
New to 1099 work? This definitive guide covers contractor status, 1099-NEC, self-employment tax, quarterly estimates, and every deduction that matters—plus how ShiftTracker™ automates mileage, expenses, and tax-ready reports so you keep more of what you earn.
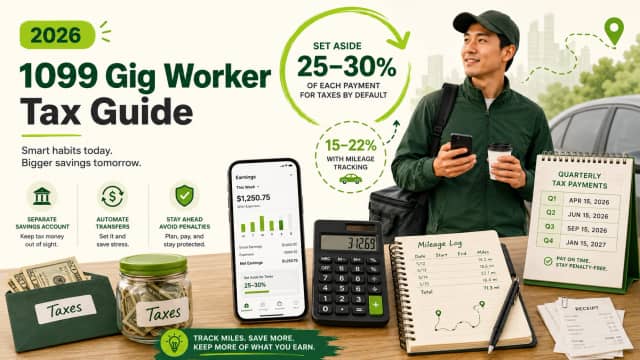
How Much Should I Set Aside for Taxes as a 1099 Gig Worker? (2026 Guide)
A 1099 gig worker should set aside 25-30% of every payment for taxes by default — but with tracked mileage at the 2026 IRS rate (72.5¢/mile Jan–Jun, 76¢ from July 1), the real number drops to 15-22%. Full breakdown with quarterly schedule, worked examples for single/MFJ/HoH filing statuses, and the 5 mistakes most drivers make.
Gig Tax Deductions 2025: Maximize Mileage & Expenses
Learn which gig expenses are deductible in 2025, how the mileage rate works, and how Shift Tracker automation prevents missed write-offs and audits.
